
The Complete Guide to Manufacturing Finance
Manufacturing is one of the most capital-intensive sectors in the…
Following an announcement by the Government on 13 July 2026, the scheme has been extended until 31 March 2030, giving businesses greater certainty when planning future investment.
Whether you’re looking for asset finance, invoice finance, business loans, refinancing or an overdraft facility, the Growth Guarantee Scheme in 2026 could help you access funding through one of the British Business Bank’s accredited lenders. In this Growth Guarantee Scheme update, we’ll explain how the scheme works, who is eligible, the types of finance available and how an independent finance broker can help you secure the most appropriate funding solution.
| Feature | Details |
|---|---|
| Scheme Extended Until | 31 March 2030 |
| Extension Announced | 13 July 2026 |
| Delivered By | British Business Bank Accredited Lenders |
| Term Loans | Up to 6 years |
| Asset Finance | Up to 3 years |
| Invoice Finance & Overdraft Facilities | Up to 6 years |
| Maximum Facility per Business Group | Up to £2 million |
| Maximum Business Turnover | £45 million |
| Personal Guarantees | May be required. Private residence excluded from security |
| Government Guarantee | Supports the lender, not the borrower |
| Business Responsibility | The borrower remains fully responsible for repayment |
The Growth Guarantee Scheme is a government-backed lending initiative designed to improve access to finance for UK businesses. Rather than lending money directly, the Government provides accredited lenders with a guarantee on part of the finance they provide. This reduces the lender’s risk and helps more viable businesses access funding.
It’s important to understand that the Government’s guarantee is for the lender, not the borrower. Your business remains fully responsible for repaying the finance under the terms of the agreement. The scheme is administered by the British Business Bank and delivered through an extensive panel of accredited lenders across the UK.
The original Growth Guarantee Scheme replaced the Recovery Loan Scheme in July 2024 and was initially scheduled to finish in March 2026. Recognising the continued demand for business finance, the Government announced on 13 July 2026 that the scheme would continue until 31 March 2030.
The extension provides greater confidence for UK businesses planning investment over the coming years and reinforces the Government’s commitment to improving access to finance for SMEs. For many businesses, this means government-backed finance remains available to support expansion, investment and working capital requirements.
Small and medium-sized businesses account for more than 99% of all UK businesses, making them the backbone of the UK economy. Despite this, many SMEs still find it difficult to secure funding through traditional lending routes. Reasons can include:
Government-backed schemes such as the Growth Guarantee Scheme help accredited lenders support businesses that have a viable proposition but may require additional flexibility when assessing applications.
One of the biggest advantages of the Growth Guarantee Scheme is its flexibility. Rather than being restricted to one funding product, eligible businesses may be able to access several different types of finance depending on their requirements.
Asset Finance
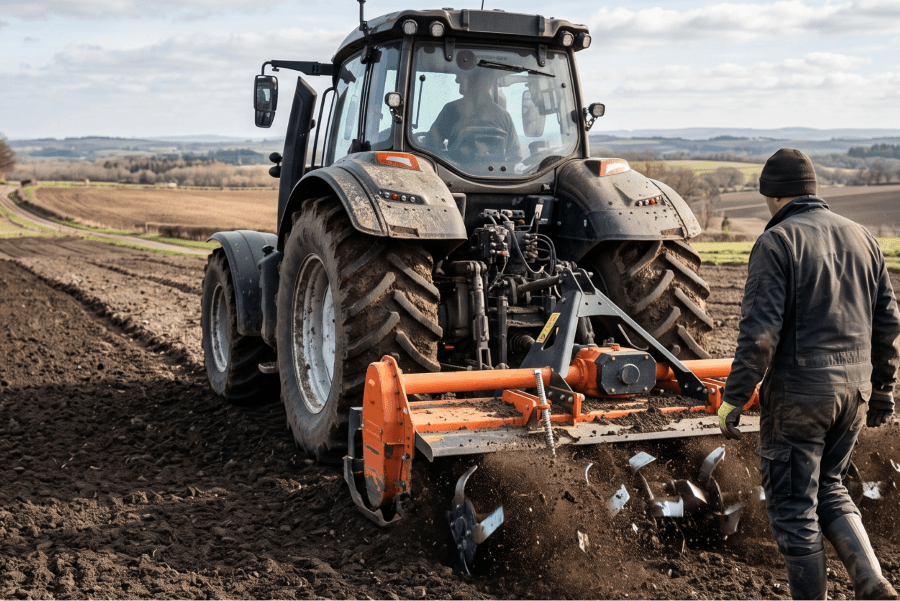
Asset Finance allows businesses to purchase essential equipment while spreading the cost over an agreed period. Rather than tying up valuable working capital, businesses can invest in:
For many businesses, asset finance provides an affordable way to invest in productivity while preserving cash flow.
Invoice Finance
Invoice Finance enables businesses to release cash tied up in unpaid invoices, providing immediate working capital without waiting for customers to pay. Late payment remains one of the biggest challenges facing UK businesses. This can help businesses:
For growing businesses with strong sales but slow-paying customers, invoice finance can provide valuable financial flexibility.
Business Loans
Business Loans remain one of the most popular finance products supported through accredited lenders. Funding can be used for:
Unlike asset finance, which is linked to a specific purchase, business loans offer greater flexibility in how the funds are used.
Refinance
Refinance allows existing borrowing to be restructured, helping businesses improve cash flow or release additional capital. Many businesses already have finance in place. Depending on the lender and eligibility criteria, refinancing may help:
For businesses with changing financial requirements, refinancing can become an important part of a wider funding strategy.
Overdraft Facilities
Overdraft Facilities supported through the Growth Guarantee Scheme provide flexible access to funding for short-term cash flow requirements. Every business experiences periods where additional working capital is helpful. Businesses commonly use overdrafts to:
Unlike a term loan, businesses only pay interest on the amount utilised.
Although each accredited lender has its own underwriting criteria, businesses will generally need to:
The scheme is available across numerous industries including construction, transport and logistics, manufacturing and engineering, agriculture, leisure and hospitality, waste management and recycling and scaffolding finance, but to name just a few.
While the Growth Guarantee Scheme provides support to accredited lenders, every finance application is still assessed on its own merits. Lenders are looking to build a complete picture of your business before making a decision. Common factors include:
Trading History
Established businesses often have access to a wider range of finance options because lenders can review previous trading performance. However, many accredited lenders will also consider newer businesses where the directors have relevant industry experience and a clear business plan.
Cash Flow
One of the most important considerations is whether your business generates sufficient cash flow to comfortably meet repayments. Strong cash flow demonstrates that your business is well managed and capable of servicing the finance.
Credit Profile
Lenders may review both the business’s credit history and, in some cases, the personal credit history of company directors. A lower credit score doesn’t automatically prevent approval. Many lenders take a balanced view by considering the overall strength of the application.
Affordability
Every lender must be satisfied that the borrowing is affordable. This means considering:
The aim is to ensure the finance supports your business rather than placing unnecessary pressure on it.
Purpose of the Funding
Lenders also want to understand how the finance will benefit your business. Applications used tore often viewed positively because they contribute directly to business growth:
Although the scheme can support many businesses, it isn’t always the most appropriate solution. For example, businesses may not benefit if they:
This doesn’t necessarily mean finance isn’t available. In many cases, an experienced finance broker like Liquid Corporate Finance can identify alternative funding options that may be more suitable.
Approaching one lender only provides access to that lender’s products and lending criteria. An independent broker works differently. Rather than relying on a single funding source, a broker compares multiple accredited lenders to identify the most appropriate solution for your circumstances. Working with a broker can provide several advantages:
Access to Multiple Lenders
Instead of completing several applications yourself, your broker can introduce your business to lenders most likely to support your requirements.
Tailored Funding Solutions
Every business is different. Whether you’re looking for asset finance, invoice finance, a business loan, refinance or an overdraft facility, the most appropriate solution will depend on your objectives.
Saves Valuable Time
Preparing finance applications and approaching lenders individually can be time-consuming. A broker manages much of the process on your behalf, allowing you to focus on running your business.
Expert Guidance
Understanding lender criteria, affordability requirements and supporting documentation can improve the quality of your application and increase the likelihood of securing finance.
For many SMEs, the scheme offers significant advantages beyond simply accessing funding.
Preserves Cash Flow
Rather than using valuable working capital to fund growth, businesses can spread repayments over an agreed period, helping maintain liquidity.
Supports Investment
Whether purchasing machinery, expanding your vehicle fleet or recruiting additional staff, access to finance enables businesses to invest when opportunities arise.
Flexible Finance Options
The scheme supports several funding products, including:
This flexibility allows funding to be tailored to the individual needs of each business.
Confidence to Plan Ahead
With the scheme now confirmed until 31 March 2030, businesses have greater certainty when planning investment and long-term growth.
Before applying for finance, it’s worth understanding the different funding products available and how they may support your business. The British Business Bank provides detailed information about the Growth Guarantee Scheme, accredited lenders and eligibility criteria.
You can also find further guidance on government-backed business finance through GOV.UK, while Companies House enables businesses to review their company filings; information that lenders commonly consider during the underwriting process. Taking time to understand your options before applying can improve your chances of choosing the right finance solution first time.
At Liquid Corporate Finance, we understand that no two businesses are the same.
Rather than offering a one-size-fits-all approach, we take time to understand your business, your objectives and your funding requirements before identifying the most suitable finance solution. Whether you’re investing in new equipment, improving cash flow, refinancing existing borrowing or looking for additional working capital, we’ll guide you through the process from enquiry to completion. With access to a wide panel of accredited lenders, we aim to make securing business finance as straightforward and efficient as possible.
Every business is different. Explore our Growth Guarantee Scheme Case Study to see how we’ve helped UK SMEs secure the funding they need to invest, expand and improve cash flow.
Has the Growth Guarantee Scheme been extended?
Yes. The Government announced on 13 July 2026 that the scheme has been extended until 31 March 2030, providing continued support for UK SMEs through accredited lenders.
Who provides the finance?
The finance is provided by accredited lenders participating in the Growth Guarantee Scheme. The Government does not lend directly to businesses.
Can I use the scheme for Asset Finance?
Yes. Eligible businesses can use the scheme to finance commercial vehicles, machinery, construction equipment, manufacturing assets and other business equipment.
Is Invoice Finance available?
Yes. Eligible invoice finance facilities can be supported through accredited lenders, helping businesses release cash tied up in unpaid invoices.
Can I refinance existing borrowing?
Potentially. Depending on the lender and the purpose of the funding, refinance facilities may be available under the scheme.
Are overdraft facilities included?
Yes. Eligible overdraft facilities can be supported, providing flexible working capital for short-term cash flow requirements.
Can start-ups apply?
Some accredited lenders will consider start-up businesses, particularly where directors have relevant industry experience and a strong business proposition.
Does the Government repay the loan if my business can’t?
No. The Government’s guarantee protects the lender, not the borrower. Your business remains fully responsible for repaying the finance.
If you’re considering asset finance, invoice finance, a business loan, refinancing or an overdraft facility, our team can help you understand whether the Growth Guarantee Scheme is the right option for your business.
Contact Liquid Corporate Finance today for a free, no-obligation discussion and discover how government-backed finance could help your business grow.




Longer term = lower payments
This enquiry will not affect your credit score